
We tell you what banks look at when granting a mortgage to an applicant. Don't waste time asking banks about their requirements: read our article to stay informed.
If you still have questions or would like a financial advisor to advise you free of charge on your real chances of getting a mortgage, just contact us and we'll assist you quickly by phone or in person.
What do banks look at to grant a mortgage?
Banks look at 3 things when granting a mortgage: the client's profile, the client's needs and the property to be mortgaged.
If the transaction passes all 3 filters, the client can get a mortgage. If any of them isn't passed, the client won't get a mortgage, although it may be possible to resolve depending on the situation.
The client's profile:
This is without doubt what banks examine most before approving a transaction. It involves several requirements the client must meet. They vary slightly from bank to bank, but in most cases they're fairly similar.
Financial solvency, ability to repay the loan, a debt ratio no higher than 35-40%, a deposit, job stability, no seizures or outstanding payments, guarantors, double guarantees and many other factors are studied meticulously by the bank.
While some lenders are satisfied if you prove your income for the last year, others ask for the last two or three.
The terms also vary depending on the bank you apply to and when you apply.
If, when you apply, interest rates are low, banks are actively lending, house prices are rising and the economy is healthy, you're more likely to get a mortgage much more easily and on better terms than in times of economic crisis and very high interest rates.
If you'd like us to study your profile free of charge and advise you on your chances of getting a mortgage and on what terms, just ask.
The client's needs:
Once the client's profile has passed the bank's filters and it considers them eligible for a mortgage, the client's needs must be studied, and this is where the problem lies.
Although banks have flexible terms, in most cases they can't offer clients a tailor-made solution, especially regarding the loan-to-value percentage.
Most clients need 80-100% of the home's value to get a mortgage, while most banks refuse to finance more than 80%, so many mortgages stall at this stage.
There are also cases where the client wants a fixed-rate mortgage to avoid surprises and the lender doesn't offer that product or has very poor terms.
By poor terms I mean a very high interest rate or one dependent on many unnecessary tie-ins.
If your bank offers you what you need, you can move on to the last step: valuing the home and buying it. Otherwise, if your bank won't lend the amount you need or doesn't offer good terms, you'll have to go from bank to bank negotiating the mortgage on the terms you need.
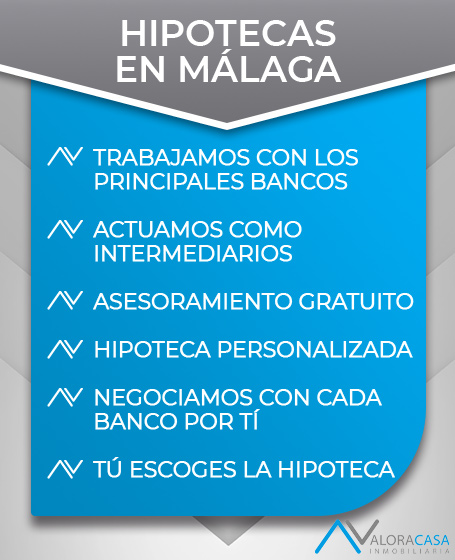
When our financial advisors submit a client's mortgage, they do so to several banks at once and negotiate with each to get a mortgage tailored to the client's needs on the best market terms.
That way we save you time and money. Time, because you don't have to go from bank to bank negotiating your mortgage; we do that. And money, because by getting you a lower interest rate you save every month on the mortgage and its costs.
The property to be mortgaged:
The third and last thing the bank looks at before granting a mortgage is examining and valuing the property to be mortgaged, on which the charge will be placed.
In this process the bank checks two things. First, the charges, defects, title issues, occupants and any limitations on the home. If the property has a charge or limitation that can't be removed, the bank will refuse the mortgage.
Finally, the bank will value the home to check it more than covers the amount the client is asking for, and to determine its value.
If all has gone well, you just need to finalise the paperwork and a few details, and you can go to the notary to sign your new mortgage.
If any step has gone wrong, you'll need to see whether it can be fixed. If the bank won't give you the mortgage, there's no solution; if the valuation comes in low, you'll need to look for another home.
Everyone has different needs and needs a different mortgage, and it's a mistake not to screen the market properly before signing with a bank.
FREE FINANCIAL ADVICE
Juan Rosado
CEO
Contact


Most searched
Offices
Sell
Buy
Rental